Buying a home is one of the biggest financial decisions you’ll ever make. While excitement is part of the process, preparation is what truly sets you up for success. If you're wondering
Dated: February 11 2026
Views: 321
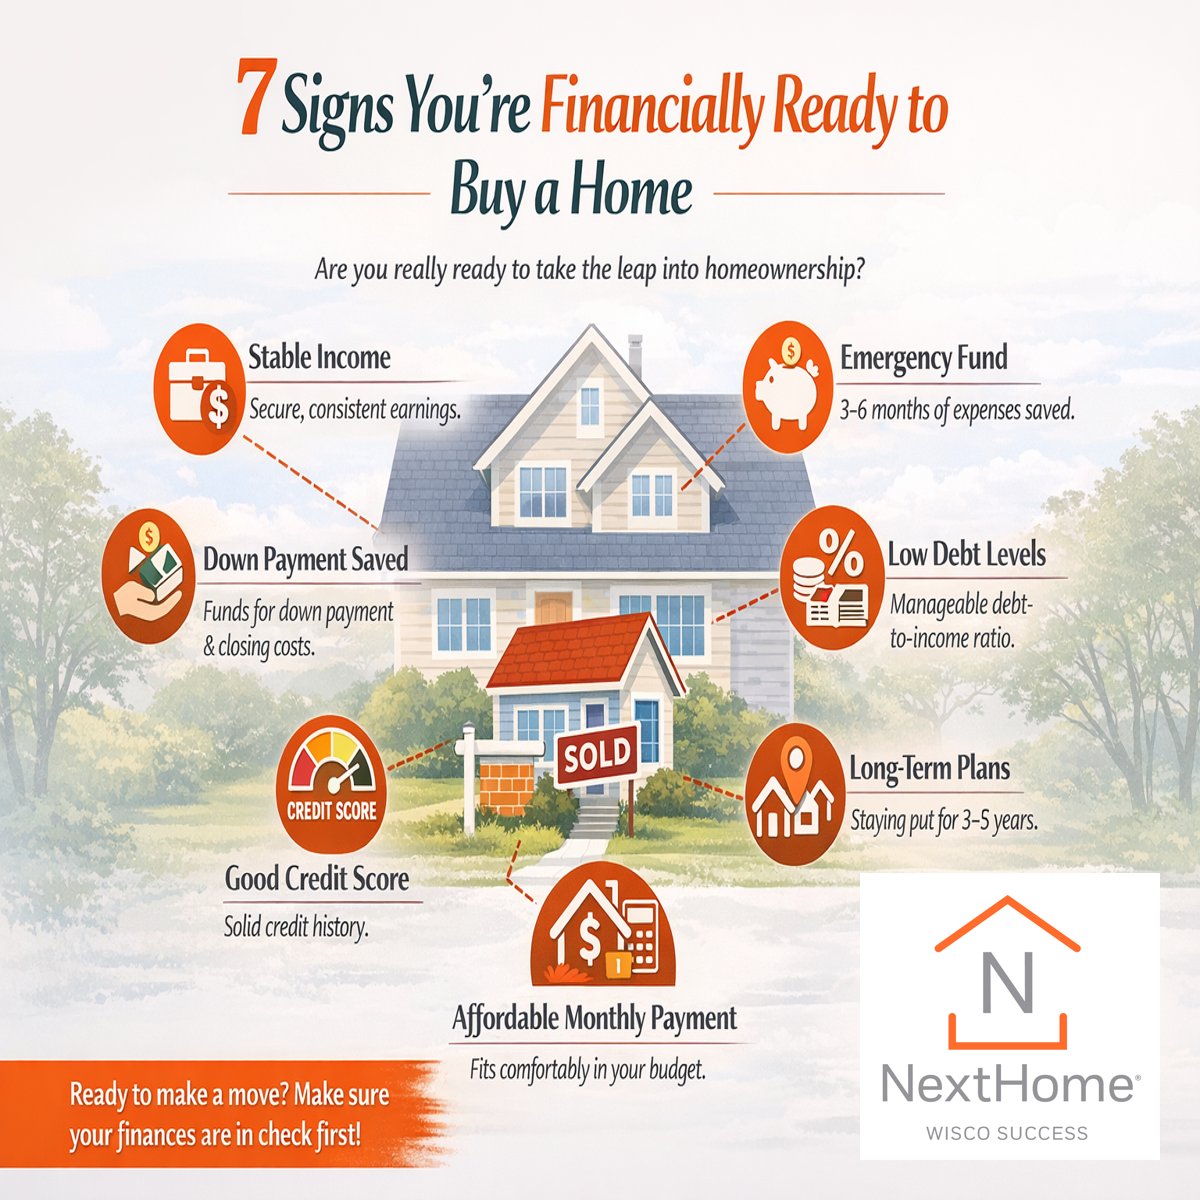
Buying a home is one of the biggest financial decisions you’ll ever make. While excitement is part of the process, preparation is what truly sets you up for success. If you're wondering whether now is the right time to make the leap, here are seven clear signs you may be financially ready to buy.
Consistency matters more than anything. Lenders look for steady employment and reliable income over the past two years. If your job situation is stable and you’re confident in your earnings, that’s a strong foundation for homeownership.
Owning a home comes with responsibilities beyond the mortgage. Having 3–6 months of living expenses saved gives you breathing room for unexpected repairs, job changes, or other surprises. A solid emergency fund protects your investment.
While 20% down is often discussed, many loan programs allow for much less. The key is having enough saved to comfortably cover:
Your down payment
Closing costs (typically 2–5% of the purchase price)
Moving expenses
The more prepared you are upfront, the less financial stress you’ll feel later.
Lenders evaluate your debt-to-income ratio (DTI), which compares your monthly debt payments to your gross income. Generally, keeping your DTI below 43% improves your approval chances. If you’re not overwhelmed by credit cards, car payments, or student loans, you’re in a healthier position to qualify.
A stronger credit score can significantly impact your interest rate. Most conventional loans require at least a 620 score, but higher scores often unlock better loan terms. If you’ve been paying bills on time and keeping credit balances low, you’re likely on solid ground.
Buying makes the most financial sense when you plan to stay in the home for at least 3–5 years. This gives you time to build equity and offset upfront costs like closing fees and moving expenses.
Your mortgage payment isn’t just principal and interest. It also includes:
Property taxes
Homeowners insurance
Possible HOA fees
Maintenance and repairs
If you’ve reviewed the full estimated monthly cost and it fits comfortably within your budget, that’s a major green light.
Being financially ready to buy isn’t about perfection — it’s about preparation. When your income is stable, your savings are in place, and your monthly budget feels manageable, homeownership becomes an exciting next step rather than a stressful gamble.
If you’re unsure where you stand, connect with an expert at NextHome Wisco Success to discuss, review, and provide clarity and confidence.
Dalton grew up in Holmen, WI and remains in the La Crosse area today. He graduated from Minnesota State University Mankato with a Sports Management degree and minor in Marketing. He has been a license....
Buying a home is one of the biggest financial decisions you’ll ever make. While excitement is part of the process, preparation is what truly sets you up for success. If you're wondering
Deciding between renting vs buying a home is one of the biggest financial decisions most people make. There is no one-size-fits-all answer. The right choice depends on your finances, lifestyle, and
Simple Improvements Before You ListWinter might not be selling season in Wisconsin, but it is the best time to prepare your home for a successful spring listing. The right upgrades done during
La Crosse has quietly become one of western Wisconsin’s most attractive housing markets. Between steady job growth, strong rental demand, and lifestyle appeal, more buyers are asking the same
 Metro MLS - Milwaukee Data provided by Metro MLS. All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. IDX information is provided exclusively for consumers personal, non-commercial use and that it may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing. The data relating to real estate for sale on this website comes in part from the Internet Data Exchange program of the Multiple Listing Service. Information is supplied by seller and other third parties and has not been verified. Real estate listings held by brokerage firms other than NextHome WISCO Success may be marked with the Internet Data Exchange logo and detailed information about those properties will include the name of the listing broker(s) when required by the MLS. Copyright ©2026 - Multiple Listing Service, Inc. - All rights reserved.
Last Updated: September 25, 2026 8:35 PM UTC
 Information should be deemed reliable but not guaranteed, all representations are approximate, and individual verification is recommended. Copyright ©2017 All rights reserved.
 REALTORS® Wisconsin Real Estate Exchange (WIREX). All information deemed reliable but not guaranteed. Information is supplied by seller and other third parties and has not been verified. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s), nor NextHome WISCO Success, nor WIREX MLS shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumer's personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing. The data relating to real estate for sale on this website comes in part from the Internet Data Exchange program of the Multiple Listing Service. Real estate listings held by brokerage firms other than NextHome WISCO Success may be marked with the Internet Data Exchange logo and detailed information about those properties will include the name of the listing broker(s) when required by the MLS. Copyright ©2026 Wisconsin Real Estate Exchange (WIREX) MLS, Inc. All rights reserved. Last Updated: September 25, 2026 4:13 PM UTC
